


 Locations



Canada is at, or very close to, the bottom of its current depressed real estate cycle — though it’s still somewhat variable depending upon asset class, region and role in the value chain — according to PwC and Urban Land Institute’s new Emerging Trends in Real Estate report.
The 20th Canadian edition of the report was compiled from information provided by hundreds of surveys and interviews with industry leaders from across the real estate spectrum.
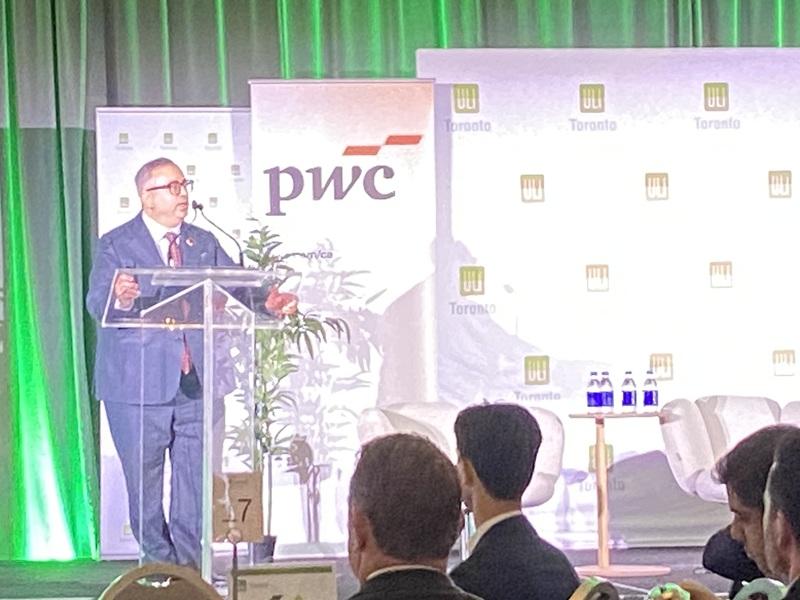
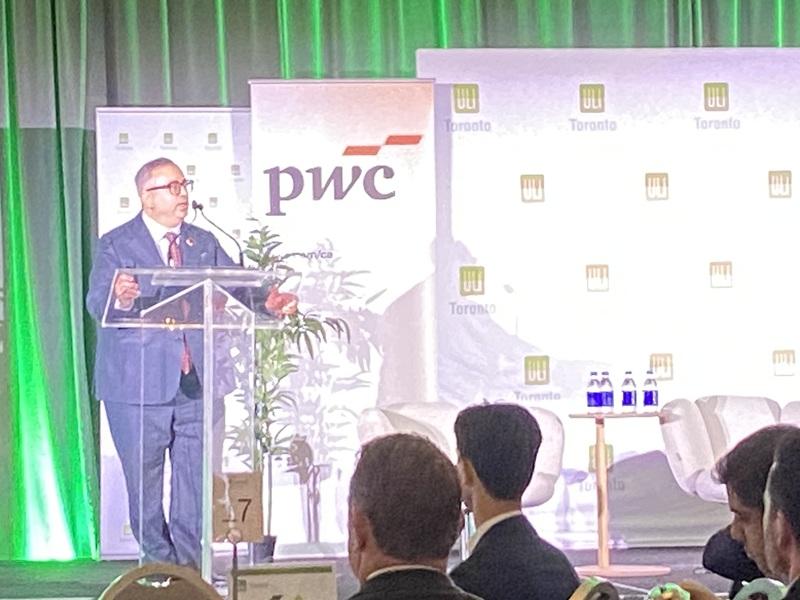
PwC Canada partner and national real estate leader Fred Cassano presented findings from the report and commented on them as part of a Nov. 6 event at Toronto’s Fairmont Royal York Hotel that also included opening remarks from KingSett Capital chief executive officer Rob Kumer, panel discussions on the commercial and multi-residential real estate sectors, and a conversation with Tricon president and CEO Gary Berman.
“The opportunities are real, but the rewards will go to organizations prepared to act on those opportunities,” Cassano said to open his presentation.
Three major observations
Sentiment to buy is at its highest in 15 years while sentiment toward selling remains near the lowest in that same period, but it has started to pick up.
Artificial intelligence (AI) emerged as the biggest disruptor that will reshape real estate from 2027 to 2029, according to 72.1 per cent of Canadian respondents.
“You need to underwrite AI like capex and measure the ROI,” said Cassano.
The top five anticipated disruptors were rounded out by: construction and labour costs; geopolitical and trade instability; energy and the power grid; and climate and insurance risk.
The asset classes showing the most momentum, in order, are seniors’ housing, retail, industrial, data centres and hospitality. Student housing and office are mid-tier while multifamily rental, new lowrise homes, condominiums and development land bring up the rear.
Infrastructure and real estate
Infrastructure investments unlocking adjacent real estate was a major theme in the report. Canada's infrastructure need is forecasted to be US$4.7 trillion by 2050, including $2.4 trillion to unlock housing, $259 billion for industrial and logistics, $89 billion for defence, $54 billion for power and data centres, and $51 billion for community infrastructure (all figures in U.S. dollars).
Cassano pointed out that power availability is a potential constraint that could hamper the needed growth.
“After years of flat demand, electricity use is expected to double by 2050,” he noted. “Data centres alone could draw 1.2 gigawatts by 2029,” which is when data centre build-out is expected to peak.
With Canada’s new emphasis on defence spending, military housing and support services for those living in it will be needed. This could give a major boost to modular construction companies.
“Sweden builds 45 per cent of its new homes in the factory, Japan 15 per cent and Canada about two per cent,” said Cassano.
“Defence needs repeatable homes fast. Factories need steady orders. That's a great match for modern methods of construction.”
Connecting real estate and healthcare
Another theme revolved around baby boomers turning 80 this year, and the 85-plus population expected to triple by 2049. Fewer than one in 10 Canadians over 75 currently live in a seniors' residence, 200,000 seniors’ rental units are needed this decade alone, and it’s projected that 450,000 long-term care units will be needed by 2040.
The majority of people still prefer to grow old at home but have easy access to healthcare, so healthcare needs to become more intertwined with real estate. People are willing to spend approximately $216 per month in extra rent for health-enabling housing, according to the report.
“Housing is healthcare and hospitals are becoming real estate partners,” said Cassano. “Pharmacies are care nodes and medical offices are handling more outpatient delivery and the logistics behind it.”
Debt, equity and foreign investment
Debt has returned to the Canadian real estate market except for development.
Fifty-six per cent of survey respondents said debt for acquisitions is in balance, up from 23 per cent in 2024. Fifty-nine per cent said debt for refinancing is in balance, up from 19 per cent in 2024. However, just 44 per cent said development debt is in balance and 46 per cent said it’s still undersupplied.
Survey respondents also believe that equity for acquisitions, developments and redevelopments is still undersupplied.
Capital will flow to operators who show net operating income (NOI) growth, measurable returns and a proven track record, while others will have to wait. This is putting a larger emphasis on operational excellence.
Foreign direct investment in Canadian real estate has been increasing, as foreign investors are filling the gap left by Canadians undervaluing their own market.
Top Canadian markets to watch
Calgary held on to top spot as the Canadian market with the best outlook for the coming year.
“It's at the beginning of an energy cycle, it’s diversifying beyond energy, it’s a central distribution hub for Canada, it’s business-friendly and has Canada's lowest tax rate,” are the reasons Cassano gave for the ranking.
Toronto, Edmonton and Ottawa maintained their spots in positions two through four, while Halifax moved up two notches due to low vacancy, a strong industrial market and the likelihood of it being a big beneficiary of increased defence spending.
“Canada isn't recovering as one market, it's recovering as many,” said Cassano.
Top investment prospects for 2027
Seniors housing is the top investment prospect for 2027 as its demand is locked in by demographics, new supply is under one per cent of total inventory and a record $8 billion in transactions have already taken place this year. Occupancy is expected to be above 90 per cent, the highest it's been in 20 years.
“It's an operating business, not a passive business, so staffing and service delivery decides returns,” said Cassano.
On a somewhat related note, medical office wasn’t far behind in second place as the care economy continues to grow.
Retail is also seen as a strong bet, as the national occupancy rate is 97.5 per cent, a decade of under-building means little new supply, long-term leases are rolling at much higher rents, and intensification can add NOI without new land.
Industrial is also looking good as rents remain stable, the national availability rate is down to 5.2 per cent after experiencing its biggest quarterly drop in five years, and there’s structural demand from e-commerce, reshoring and defence procurement.


 Industry Events
 Locations

