


 Locations




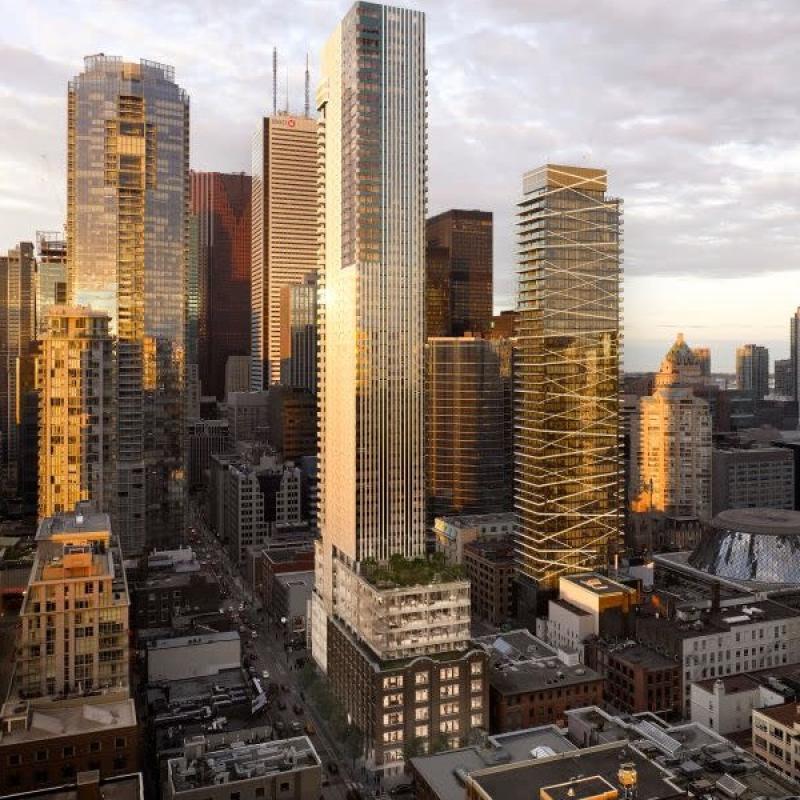
Allied Properties REIT (AP-UN-T) has agreed to sell its Toronto House complex as it continues efforts to strengthen its balance sheet.
The office-focused REIT made the announcement in its Q3 financial results which were released Wednesday evening.
Toronto House is a 58-storey mixed-use tower at 19 Duncan St., a few blocks from the CN Tower, which Allied co-developed in partnership with Vancouver-based Westbank.
In addition to its residential component of 464 market rental units, the building houses approximately 154,000 square feet of office space along with ground-level retail and restaurant uses.
Allied achieved full ownership of the asset through two transactions in 2024, pegging the total acquisition cost of the additional 50 per cent stake at $271.5 million in its 2024 year-end report.
Allied said the transaction is subject to Competition Act approval and expected to close in Q4. No details on the buyer were released.
Continuing to reduce leverage
Allied also announced it will be slashing its distributions by 90 per cent in order to divert $126 million to reduce its debt.
The cut will bring distributions down to $0.006 per unit per month, or 7.2 cents a year.
"Our leverage remains too high," Allied president and CEO Cecilia Williams said on a conference call to discuss the quarterly results. "We need to reduce it while the cash flow benefit of our leasing activity builds. That is why we're retaining more cash and accelerating dispositions."
Allied has exceeded its target of $500 million in dispositions this year, she added.
In its quarterly report, Allied said dispositions had totalled $336 million in gross proceeds to date, but the Toronto House disposition "went firm" subsequent to the quarter, bringing "overall gross proceeds from dispositions to $660 million," suggesting an agreed sale at $324 million, although this figure was not explicitly stated.
These proceeds will be directed toward the REIT's debt, and Allied is maintaining its year-end net-debt-to-EBITDA target in the mid-11x range.
Allied also increased its multi-year disposition target by $750 million to $1.5 billion.
"As we select properties for sale, we'll balance near-term deleveraging objectives with strategic importance and long-term return potential," Williams said. "Our objective is to reduce debt and concentrate our capital in the properties we believe offer the strongest future returns."
Progress on leasing
Allied said leasing momentum is improving in the office sector, although the market is increasingly divided between higher-quality and lower-quality properties.
Allied's leasing pipeline reached 1.95 million square feet, its largest since Allied began reporting the metric, up 49 per cent since the start of the year and 12 per cent from Q2. It included one million square feet of new opportunities and 950,000 square feet of renewals.
"Our portfolio continues to outperform the market in Montreal, Toronto, Kitchener and Calgary, and our Vancouver portfolio is in line with the market because of higher vacancy in our Gastown submarket," chief operating officer J.P. MacKay said on the conference call.
"Our occupied and leased area in Q3 ended slightly higher than Q2, at 84.9 per cent and 86.8 per cent, respectively, and ahead of the expectations communicated on our Q2 earnings call. Importantly, occupancy increased despite Sun Life vacating 56,000 square feet at our de Gaspé portfolio in Montreal, our largest known non-renewal of 2026."
MacKay said Allied is in advanced negotiations to backfill up to 45,000 square feet of that space with a lease commitment in Q4 or early next year.
Average total leasing costs year to date are $5.19 per square foot per annum, he said, compared to $7.01 in 2025. Average leasing costs for new leases are $6.74 per square foot per annum, and $3.77 for renewals.
MacKay said Allied believes the office market will stabilize in two phases. "Phase one is underway and driven by higher fiscal utilization, flight to quality, and return to office mandates," he said.
"Phase two will be driven by improved economic output and employment growth in office-using sectors, propelling further expansion and fostering demand for new entrants to the Canadian market that have been largely absent for five years."
No new development, not considering a sale
Allied will undertake no new development "for the foreseeable future," the company said in the quarterly results. KING Toronto, a mixed-use residential and commercial development in downtown, is its sole ongoing project and slated for completion in H2 2027.
While Allied raised its year-end occupancy outlook to 86.0-86.5 per cent on the back of leasing activity, the impact of accelerated property sales and lower cost capitalization prompted the REIT to lower its 2026 financial guidance.
Net operating income (NOI) is now forecast at $300 million to $305 million (down from $310 million to $320 million) and funds from operations (FFO) at $170 million to $175 million (down from $185 million to $200 million).
Allied also disclosed that an anticipated $125 million partial repayment on its 150 West Georgia loan has been pushed past December 2026 due to construction delays.
Taking questions at the end of the conference call, Williams said while Allied is constantly reviewing its strategy, a sale of the REIT is not on the table.
"At this point, we're always assessing all of the strategic alternatives available to us, she said. "If you mean specifically a sale of the company, now is not the time pursue that. We would not achieve value for our unit holders."


 Industry Events
 Locations

